UM + UIM required
Connecticut coverage menu: liability and UM/UIM required, conversion coverage offered
Connecticut makes uninsured and underinsured motorist coverage part of every policy. You can lower it with a signed form, but not below 25/50. Here is how the limits, conversion coverage and stacking rule work.
By CoverOath Editorial Team Updated 6 min read
The promise, in short
Connecticut requires 25/50/25 liability and uninsured/underinsured motorist coverage on every policy. UM/UIM matches your bodily injury liability limits unless a named insured asks in writing, on a signed informed consent form, for less; it can never go below $25,000 per person and $50,000 per accident. Insurers must also offer underinsured conversion coverage. There is no PIP. The Connecticut Insurance Department answers at 800-203-3447.
- Minimum liability
- 25/50/25
- PIP and MedPay
- No PIP; MedPay optional
- UM/UIM
- Required, at least 25/50
Connecticut coverage menu
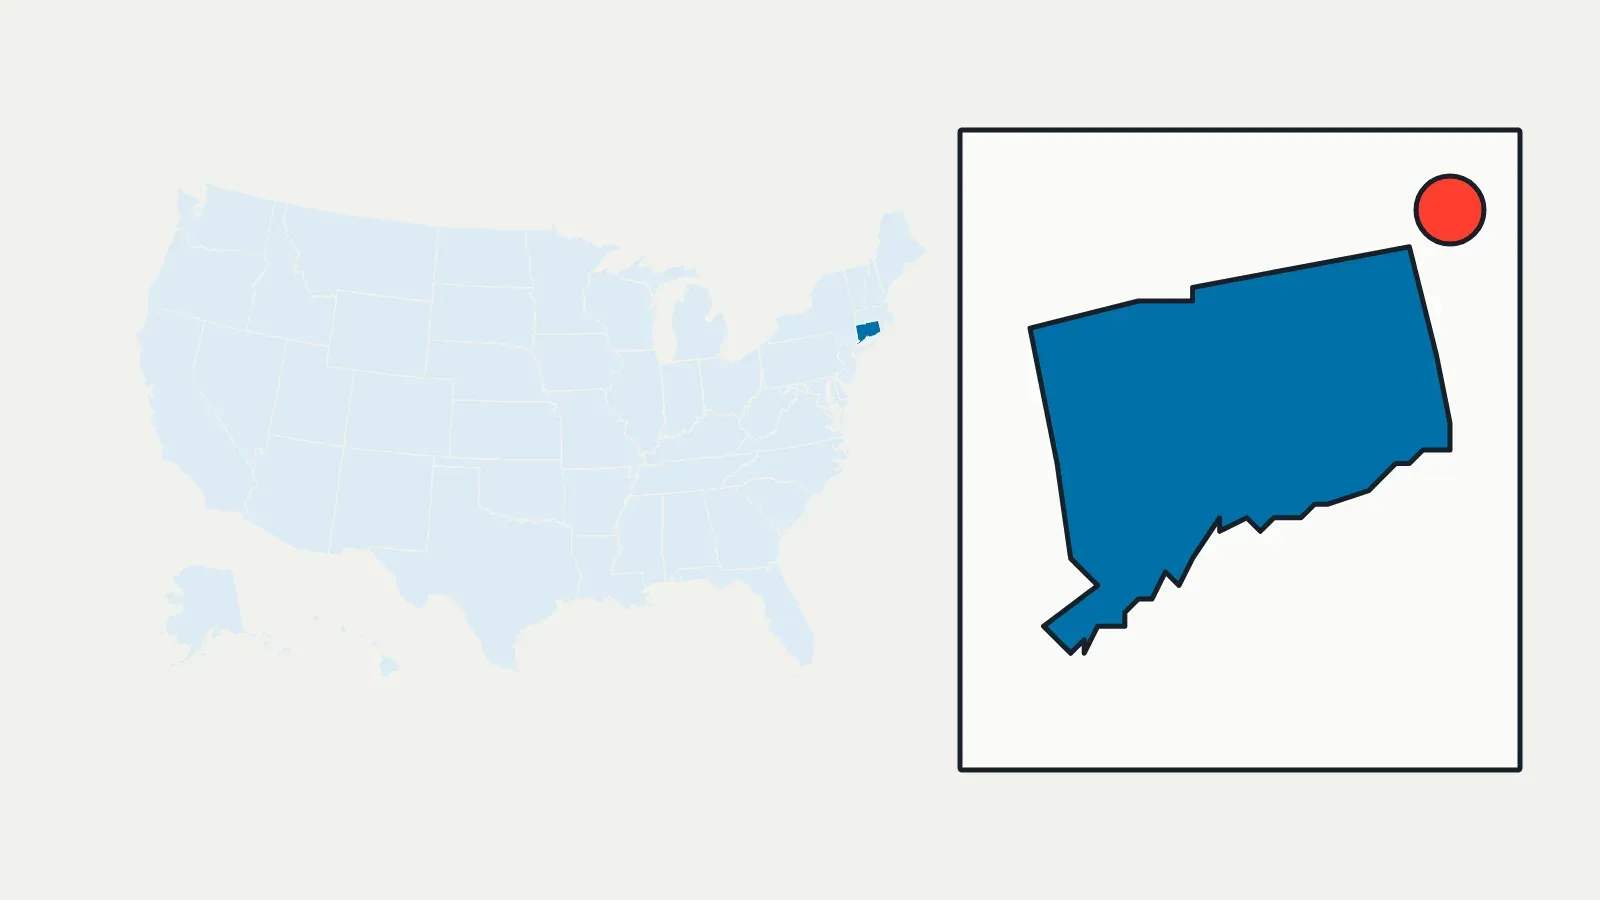
What a Connecticut policy must carry
The Connecticut Insurance Department lists two required coverages: liability at the limits in C.G.S. §14-112, and uninsured/ underinsured motorist coverage of at least $25,000 per person and $50,000 per accident.
| Coverage | Minimum | What it pays |
|---|---|---|
| Bodily injury liability | $25,000 / $50,000 | People you injure, per person / per crash |
| Property damage liability | $25,000 | Other people's cars and property |
| Uninsured/underinsured motorist | $25,000 / $50,000 | Your injuries caused by a driver with no or too little insurance |
The Department urges drivers to consider limits higher than these minimums. Any award above your liability limits is yours to pay. The liability limits guide explains how people choose.
UM/UIM limits and the informed consent form
Under C.G.S. §38a-336, every auto liability policy must provide uninsured and underinsured motorist coverage. The statute lets you lower it, not remove it.
- Default: your liability limits. UM/UIM limits equal your bodily injury liability limits unless a named insured asks in writing for a lower amount.
- Floor: 25/50. The lower amount cannot go below the §14-112 minimum.
- A signed form. A request for less takes effect only with a signed informed consent form, whose heading begins: "When you sign this form, you are choosing a reduced premium."
- Room to go higher. On request, the insurer must offer UM/UIM limits of twice your bodily injury liability limits.
Underinsured conversion coverage
C.G.S. §38a-336a requires every insurer to offer underinsured motorist conversion coverage for an extra premium. If you buy it, it replaces the ordinary underinsured coverage.
Ordinary UIM
The standard coverage under §38a-336. Unlike conversion coverage, it does not carry the statute's promise that payments from the at-fault driver will not reduce it.
Conversion UIM
Is not reduced by payments from the at-fault driver or any third party, so it pays on top of what that driver's insurer paid, up to your limit.
For each new policy, the insurer must disclose the availability, the premium and a description of conversion coverage, shown conspicuously with the informed consent form. Your choice carries over to renewals until a named insured changes it in writing.
An example of what "not reduced" means: with $100,000 of conversion coverage, if the at-fault driver's insurer pays you $25,000 and your damages are larger, your conversion coverage still has its full $100,000 available for the damages above that $25,000, after the at-fault driver's limits are exhausted.
UM/UIM rules that limit or protect the payment
- No stacking. Section 38a-336(d) says limits for several vehicles or policies are not added together for one accident. When you ride in a car you do not own, that car's coverage pays first, your own policy second, and others after. See how stacking works.
- No reduction for Social Security disability. Those benefits cannot reduce your UM/UIM limits.
- Payments to others. On policies issued or renewed on or after October 1, 2015, your limits cannot be reduced by what the at-fault driver paid other people.
- Arbitration and time limits. Claims over $40,000 that go to arbitration use a three-arbitrator panel, and the time to bring a claim is at least three years.
No PIP; MedPay is optional
Connecticut is a fault state with no personal injury protection requirement. Medical payments coverage is not among the coverages the Department lists as required, so it is an option you add. Damage to your own car from an uninsured driver is paid by collision, if you carry it.
Where to check and complain
- Read your declarations page for your liability and UM/UIM limits, and whether conversion coverage is listed.
- Ask the insurer for the signed informed consent form if your UM/UIM limits are lower than your liability limits.
- Contact the Connecticut Insurance Department at 800-203-3447 (Consumer Affairs, 860-297-3900) if an insurer will not explain a coverage or claim decision.
Questions drivers ask
Is uninsured motorist coverage required in Connecticut?
Yes. Every policy must include uninsured and underinsured motorist coverage of at least $25,000 per person and $50,000 per accident. You cannot reject it, only lower it with a signed form.
What is underinsured conversion coverage?
An optional, extra-premium form of UIM that insurers must offer. It is not reduced by what the at-fault driver's insurer paid you.
Can I stack UM/UIM coverage in Connecticut?
No. Section 38a-336(d) bars adding limits across vehicles or policies for one accident. See stacking.
What is the minimum car insurance in Connecticut?
25/50/25 liability plus uninsured/underinsured motorist coverage of at least 25/50.
Drawn from
- Connecticut Insurance Department — What is auto insurance? (Apr. 12, 2023)
- Connecticut General Statutes, Chapter 700 (§38a-336, UM/UIM; §38a-336a, conversion coverage)
- Connecticut Office of Legislative Research — Auto insurance requirements by state (2017-R-0050)
Facts on this page were checked against these sources on November 15, 2026. Connecticut's minimum liability limits were 20/40/10 when the 2017 legislative research report was written and are 25/50/25 today.
Have this coverage priced
CoverOath doesn't sell insurance. Answer five questions and CoverOath passes your request to licensed insurance agents and insurers, who can quote the coverage; you decide whether to buy anything.
- 1 The coverage you want priced.
- 2 Where an agent can reach you, and your consent.
- 3 A licensed insurance agent or insurer contacts you with a quote. Nothing is bought until you agree.
CoverOath is not paid by you. The licensed insurance agents and insurers who contact you set their own prices and terms. How we make money.
Adjacent layers
-
Core coverage
Underinsured motorist coverage (UIM)
Pays your injuries above the at-fault driver's limit. Added-on UIM stacks on their payment; offset UIM subtracts it.
-
Core coverage
Uninsured motorist coverage (UM)
Pays your injuries when an uninsured or hit-and-run driver is at fault. Required in about 20 jurisdictions.
-
Fine print
Stacking UM/UIM coverage
Whether UM limits on several cars add up. Pennsylvania and Florida stack by default; California bans it.